1 Percentage Point Gap in DRAM, 32 Percentage Point Gap in HBM... SK Hynix and Micron Diverge in Market Share
IT DAILY ·
✦ AI Summary
According to Counterpoint Research, HBM demand and server DRAM demand both increased in the second quarter of this year as investment in AI servers expanded.
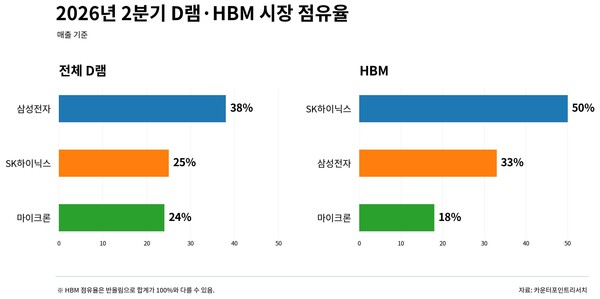
The global DRAM market shares by revenue in the second quarter of this year were Samsung Electronics at 38%, SK Hynix at 25%, and Micron at 24%.
HBM revenue shares were SK Hynix at 50%, Samsung Electronics at 33%, and Micron at 18%, and the gap between SK Hynix and Micron was much wider than in overall DRAM.
According to Counterpoint Research, in terms of revenue in the second quarter of this year, rising HBM demand and growing server DRAM demand appeared alongside each other amid increased investment in AI servers. However, the pace of revenue growth for each vendor differed depending on product prices and shipment mix.
As a result, the global DRAM market shares by revenue in the second quarter of this year were Samsung Electronics at 38%, SK Hynix at 25%, and Micron at 24%. The gap between SK Hynix and Micron in the global DRAM market narrowed from 7 percentage points in the first quarter to 1 percentage point in the second quarter, with SK Hynix's share falling from 29% to 25% over the same period and Micron's share rising from 22% to 24%. In HBM market share, SK Hynix held a 32 percentage point lead over Micron.
According to DRAM and HBM market share data by revenue for the second quarter of this year released by Counterpoint Research on the 2nd, the gap in market share between companies was much wider in HBM than in overall DRAM. Second-quarter HBM revenue shares were estimated at 50% for SK Hynix, 33% for Samsung Electronics, and 18% for Micron. Counterpoint Research said the share gap between SK Hynix and Micron was 1 percentage point in overall DRAM but 32 percentage points in HBM.
By contrast, in the overall DRAM market by revenue for the second quarter of this year, as announced by Counterpoint Research, the gap narrowed. The narrowing of the overall DRAM gap was attributed to rising DRAM prices and differences in shipment mix by product.
Behind this trend was increased investment in AI infrastructure. As a result, demand for HBM used in accelerators increased, and demand for high-capacity server DRAM also increased.
This increase in demand stemmed from expanding demand for LLM training and AI inference. As a result, shipments of HBM3E increased, shipments of LPDDR5X increased, and shipments of RDIMM also increased.
According to TrendForce, global DRAM industry revenue in the second quarter reached USD 154.73 billion, up 59.5% from the previous quarter. Suppliers' inventories were low, and additional supply was concentrated in server products.
The effect of rising DRAM prices varied by company, with SK Hynix and Micron showing differences in the scale of revenue growth and share changes. SK Hynix's second-quarter DRAM revenue was USD 38.59 billion, up 37.9% from the previous quarter, and its market share was 24.9%. Micron's DRAM revenue was USD 36 billion, up 65.5% from the previous quarter, and its market share was 23.3%.
TrendForce said SK Hynix had the highest HBM share of DRAM bit shipments among the top three companies. However, it said the impact of the HBM mix limited the increase in SK Hynix's average selling price (ASP) relative to others.
TrendForce explained that Micron boosted revenue by prioritizing high-priced server DRAM within limited production capacity. As a result, according to TrendForce, the share gap between SK Hynix and Micron narrowed to 1.6 percentage points.
Separately, in the HBM market, Samsung Electronics' rise in market share stood out. Under Counterpoint's data, SK Hynix's HBM revenue share fell from 64% in the second quarter last year to 50% in the second quarter this year, while Samsung Electronics' HBM revenue share rose from 15% to 33% over the same period. Micron's HBM revenue share under Counterpoint also fell from 21% to 18% over the same period.
As quarterly market share swings widened, the quarterly share figures showed Samsung Electronics rising and SK Hynix falling. Samsung Electronics' share rose 12 percentage points from 21% in the first quarter to 33% in the second quarter, while SK Hynix's share fell from 58% to 50% over the same period.
Counterpoint said most HBM revenue is generated by HBM3E and forecast that HBM4 shipments will begin in earnest from the second half of the year. It also projected that DRAM prices will continue rising in the fourth quarter, while TrendForce expects supply shortages to persist as production capacity is prioritized for high-performance products for AI servers, leading to a 10% to 15% increase in fourth-quarter contract prices for standard DRAM compared with the previous quarter.
Source: IT DAILY · Kim Byeong-ju
Original: https://www.itdaily.kr/news/articleView.html?idxno=241991
References
This article was produced with the help of an automated content generation algorithm.
Source: IT DAILY
View originalThis article was summarized and organized by BizCrush based on the original article from IT DAILY. For exact quotations and full details, please refer to the original article.